 For years, the crypto tax return was the filing people quietly skipped, reasoning that HMRC couldn’t see their exchange accounts anyway. That era is over. Since January 2026, crypto platforms have been collecting customer transaction data for automatic reporting to HMRC under the Cryptoasset Reporting Framework, which means the question has flipped: it’s no longer whether HMRC will know about your crypto, but whether your tax return tells the same story as the data arriving beside it.
At Crypto Tax Solution, filing season is when half our new clients arrive, usually with a carrier bag of CSV exports and a deadline. So here’s the complete, practical guide to the 2025/26 crypto tax return: who has to file, where crypto actually goes on the form, the £50,000 proceeds rule that catches people who owe nothing, and the 7 steps that take you from exchange history to a filed return by 31 January 2027.
Who Needs to File a Crypto Tax Return for 2025/26?
A crypto tax return is needed for the year ended 5 April 2026 if any of these applied to you:
- Your gains exceeded the £3,000 annual exempt amount. Remember that disposals include swapping one coin for another, spending crypto and gifting it to anyone other than a spouse or civil partner, not just selling for pounds.
- You’re already in Self Assessment and your total disposal proceeds exceeded £50,000, even if your gains were below the allowance or you made a loss. This proceeds rule is the one that catches high-volume traders who genuinely owe nothing.
- You had crypto income (staking, mining, airdrops for services) above the £1,000 trading and miscellaneous income allowance, the territory we covered fully in our staking rewards tax guide.
- You want to claim losses. Losses only become usable once claimed, the clock runs four years, and the crypto tax return is the normal place to do it. In a losing year this is a reason to file, not an exemption from it.
A pattern worth naming: for many investors, 2025/26 is their first crypto tax return not because they traded more, but because the thresholds finally caught them. The £3,000 annual exempt amount is small enough that one decent take-profit moment crosses it, a busy trading habit crosses £50,000 of proceeds surprisingly fast at today’s prices, and steady staking walks through the £1,000 income allowance in instalments. If you’ve filed nothing before, none of this is alarming; it just means registration and a first return, done properly, this winter.
If none of those apply and you simply bought and held, there’s usually nothing to report, and GOV.UK’s guidance on tax when you sell cryptoassets confirms the tests. When in doubt, check properly rather than guessing, because the cost of a wrong “no” has gone up considerably now the data flows.
Crypto Tax Return Deadlines for 2025/26
| What | Deadline |
|---|---|
| Register for Self Assessment (if newly required) | 5 October 2026, now passed, so register immediately if you missed it |
| File online and pay | Midnight, 31 January 2027 |
| Late filing | £100 penalty from day one, escalating with time, even if no tax is due |
One timing note specific to crypto: if you sold a UK residential property you’d bought with crypto profits, that property has its own 60 day reporting rule, but crypto disposals themselves have no equivalent. Everything crypto waits for the Self Assessment cycle, which is precisely why January surprises are so common: a whole year of trading lands as one bill.
Where Crypto Actually Goes on the Tax Return
A crypto tax return isn’t a separate form; it’s the normal Self Assessment return with crypto entered in the right places:
- Capital gains and losses go in the capital gains pages (SA108), which now include dedicated rows for cryptoassets, so crypto disposals are reported separately from shares and property rather than buried in “other assets”. You’ll report numbers of disposals, total proceeds, allowable costs, gains and losses, and attach or hold your computations.
- Crypto income (staking, mining, service airdrops) goes in the miscellaneous income section, or as trading income in the rare cases the activity amounts to a trade.
- Loss claims are made in the capital gains pages too, which starts their four year clock and banks them for the future.
- Employment income paid in crypto belongs with employment income, valued in pounds when received.
The dedicated cryptoasset boxes matter more than they look: they let HMRC’s systems compare your declared crypto figures directly against the platform data arriving under CARF. A return that reports crypto honestly in the right boxes reads as clean; crypto activity folded invisibly into other lines, or missing entirely, is what the matching software is built to flag.
The 7 Steps to a Correct Crypto Tax Return
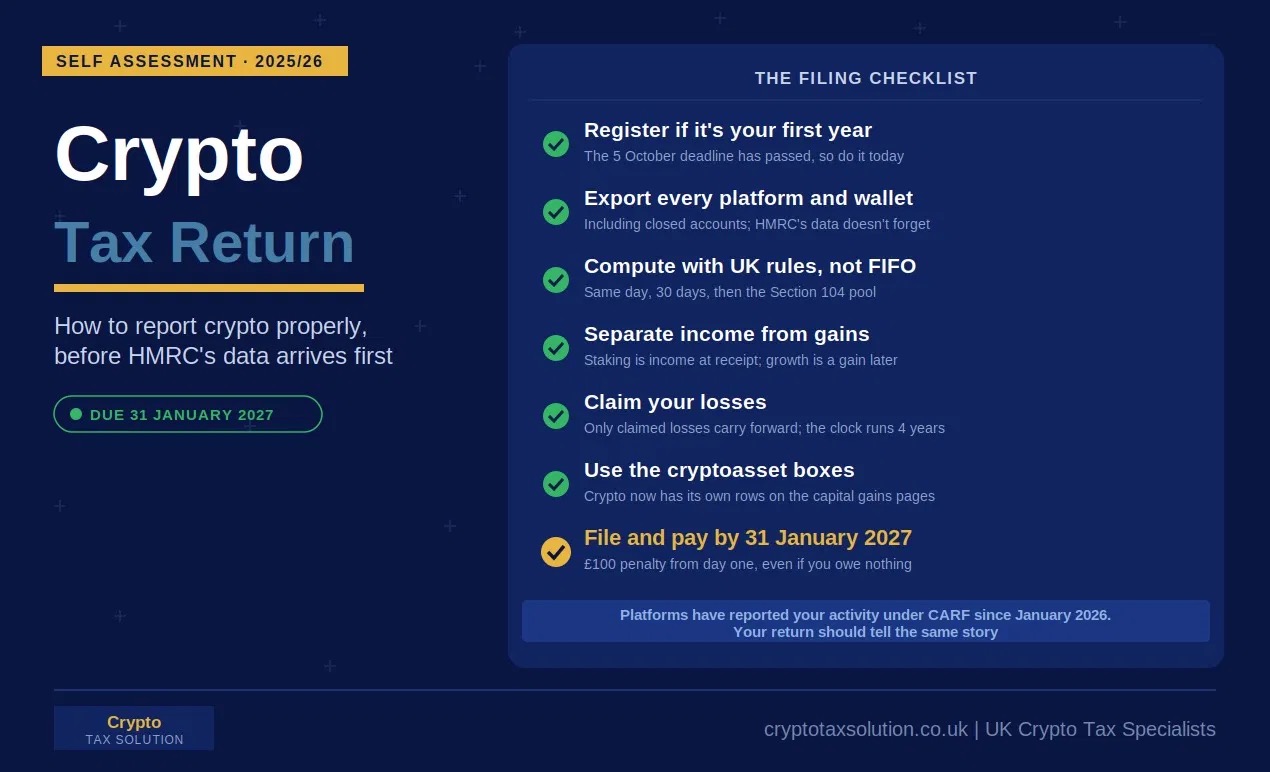
- Confirm a crypto tax return is needed, and register if so. The tests above decide it. If 2025/26 is your first Self Assessment year, register with HMRC now; the 5 October deadline has passed, but prompt registration followed by on-time filing usually keeps the damage at zero.
- Export everything. Every exchange, every wallet, every chain, including closed accounts and platforms you left years ago. Missing history is the single biggest cause of wrong numbers, because UK matching rules need your whole acquisition history, not just this year’s trades.
- Compute with UK rules, not defaults. Disposals are matched same day, then 30 days, then against your Section 104 pool, valued in pounds at each transaction. Many crypto tax tools default to US methods like FIFO, which produce confidently wrong UK figures until you change the setting. The full framework is in our UK crypto tax guide.
- Separate income from gains. Rewards and service airdrops are income at receipt value; their later disposal is a gain or loss measured from that value. Mixing the two, or taxing the same value twice, are the classic DIY errors.
- Claim your losses. Realised losses, and negligible value claims where tokens died, reduce this year’s gains or carry forward once claimed. Filing a loss year protects relief you’ll want later.
- Fill in the boxes and keep the workings. Enter the crypto figures in the cryptoasset rows, income in its section, and retain the full computation behind every number. HMRC can ask for it, and a tidy computation closes questions fast.
- File and pay by 31 January 2027. Then set up records properly for 2026/27, because next year’s return is already accumulating.
The Payment, and One Pleasant Surprise
Here’s a detail that genuinely cheers people up. Self Assessment’s payments on account system, which makes many filers pay 150% of their bill in January, is calculated only on income tax and Class 4 National Insurance. Capital Gains Tax never enters payments on account. So an investor whose crypto tax return is mostly gains pays the CGT once, on 31 January, with no advance payments towards next year layered on top.
The flip side: substantial staking or mining income is income tax, so it can create or inflate payments on account, meaning heavy earners of crypto income should check the full January figure early rather than assuming the bill equals the tax. Either way, the arithmetic is knowable months in advance, which is the strongest argument for filing in autumn: you learn January’s number while there’s still time to plan for it, and refunds from over-withholding arrive sooner too.
5 Mistakes That Invite an HMRC Letter
- Reporting only the exchanges that emailed you a statement. HMRC’s data doesn’t depend on what you downloaded. The return must cover all platforms, including the defunct and the foreign.
- Forgetting that swaps are disposals. A year of coin-to-coin trading with no pounds withdrawn can still produce a five figure gain. This single misunderstanding fills more nudge letters than any other.
- Ignoring the £50,000 proceeds rule. Owing no tax doesn’t always mean reporting nothing. High-volume traders already in Self Assessment must report disposals once proceeds pass the threshold, losses and all.
- Using a tool’s default settings. FIFO figures on a UK crypto tax return are wrong figures, even when the tool’s PDF looks authoritative. Check the method says UK (share pooling with the 30 day rule) before trusting anything it prints.
- Silence after visible activity. Filing returns for years, then stopping the crypto pages the year you traded hardest, is exactly the pattern that triggers correspondence. If the data will show activity, the return should explain it, even when the explanation is “losses, claimed here”.
The Records HMRC Expects You to Keep
Behind every crypto tax return sits the evidence. For every acquisition and disposal: the date, the asset and quantity, the value in pounds at the time, the other side of the transaction, and the platform or wallet involved, plus bank statements showing transfers in and out of the crypto world. Keep them for at least five years after the filing deadline. In practice this means letting software maintain a live record rather than reconstructing each January, because the reconstruction gets harder every year as platforms close and APIs forget. The habit costs minutes a month; the archaeology costs days.
Two practical notes on evidence. First, screenshots are better than nothing but worse than exports: CSV or API records carry the detail HMRC’s checks expect, so capture them while accounts are open. Second, when a platform has already collapsed, gather what exists now (emails, statements, blockchain explorer records for your addresses) rather than waiting; evidence for a crypto tax return only ever gets harder to obtain, never easier.
Why This Is the Year to File Your Crypto Tax Return Early
Early filing is always sensible; this year it’s strategic. The deadline is nearly four months away as we publish, which sounds like plenty until you’ve met a crypto transaction history. Three reasons stand out for moving now.
The data comparison has begun. With CARF collection running since January 2026 and the first platform reports reaching HMRC in 2027, the 2025/26 crypto tax return lands just as HMRC’s visibility peaks. A return filed early, accurately and in the right boxes positions you as exactly the kind of filer the compliance campaigns skip past. A rushed January return with round numbers in the wrong rows does the opposite.
Reconstruction takes longer than people budget. A crypto tax return covering multiple exchanges, a DeFi experiment and a wallet or two routinely needs weeks of data gathering before computation even starts, and support tickets to defunct platforms don’t move faster in December. Starting in October converts a January crisis into an autumn project.
The number becomes plannable. Knowing the bill in October means three months to arrange the cash, consider whether to realise losses before 5 April 2027 against next year, and decide calmly whether anything in your approach should change. Knowing it on 30 January means paying whatever it says. The tax is identical either way; the control is not.
How Crypto Tax Solution Handles Your Return
This is our core service in filing season. We reconstruct your complete transaction history across exchanges, wallets and chains, run the computations under the UK matching rules, separate income from gains correctly, claim every loss and relief you’re entitled to, prepare the crypto pages and the rest of your Self Assessment, and file the lot with the workings retained and ready if HMRC ever asks. Complex histories (DeFi, collapsed platforms, missing years) are precisely what we untangle, quietly and without judgement, and if you’ve never filed before we handle the registration too. To get your crypto tax return filed early and the January number known in advance, get in touch now, while the deadline is still comfortably far away.
This article is general guidance based on the rules at the time of writing. Reporting requirements, thresholds and forms can change, and your circumstances are unique, so please seek advice tailored to you before filing.
Frequently Asked Questions
When is the crypto tax return deadline for 2025/26?
Online filing and payment are due by midnight on 31 January 2027, covering the tax year that ended 5 April 2026. If you’ve never filed before, you also needed to register by 5 October 2026, so register immediately if that’s been missed.
Do I need to report crypto if I made no profit?
Sometimes, yes. If you’re already in Self Assessment and your total disposal proceeds exceeded £50,000, you report the disposals even with no gain. And filing in a loss year is how losses are claimed and preserved, which usually makes it worthwhile anyway.
Where does crypto go on a Self Assessment tax return?
Capital gains and losses go in the capital gains pages, which include dedicated cryptoasset rows, with your computations kept behind the figures. Staking, mining and service airdrop income goes in the miscellaneous income section, or trading income where the activity amounts to a trade.
Does HMRC know about my crypto?
Increasingly, yes. Since 1 January 2026 crypto platforms have been collecting customer transaction data for automatic reporting to HMRC under the Cryptoasset Reporting Framework, alongside data HMRC already obtains from exchanges directly. The safe assumption is that your platform activity is visible.
Do crypto gains create payments on account?
No. Payments on account are calculated only on income tax and Class 4 National Insurance, so Capital Gains Tax on crypto is paid once, on 31 January, with no advance payments. Crypto income such as staking rewards is income tax, though, so large amounts can create payments on account.
I only swapped coins and never withdrew pounds. Do I still file?
Quite possibly. Swapping one cryptoasset for another is a disposal for Capital Gains Tax, so a year of active coin-to-coin trading can produce reportable gains (or claimable losses) even though your bank account never saw a penny.
Can I use software for my crypto tax return?
Good software helps enormously with the record keeping and arithmetic, provided it’s set to UK rules: share pooling with same day and 30 day matching, not FIFO. For complex histories, a specialist reviewing the software’s output before it goes on the return catches the errors that generate HMRC letters.
What records do I need for a crypto tax return?
Dates, assets, quantities, pound values at the time, counterparties and platforms for every acquisition and disposal, plus bank statements showing transfers, kept for at least five years after the filing deadline. Maintaining them continuously beats reconstructing them every January.